Objecting to a KRA Assessment in Kenya: The Objection and Appeal Route
Understand the objection deadline, what makes a valid filing, what KRA must decide and how to appeal.
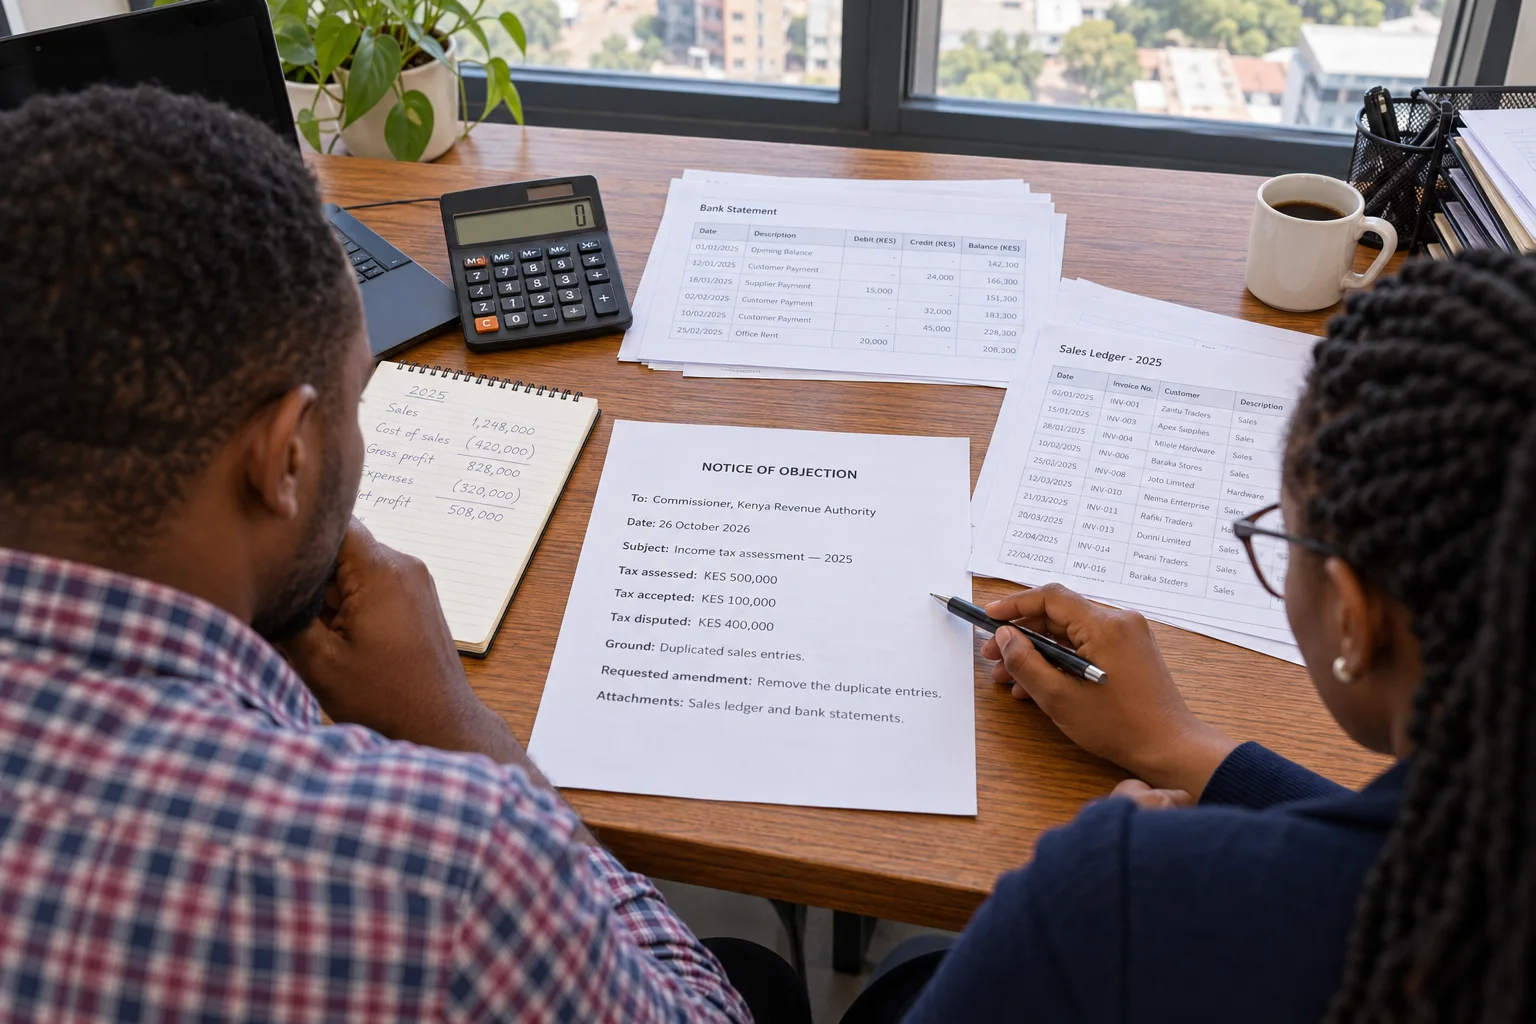
An assessment from KRA can arrive with a figure that matches nothing in your records. It carries a due date and a window in which you can answer it, and the clock starts when the notice is served on you, not when you open the letter.
Kenya runs a self-assessment system. You file your return and you remain responsible for supporting it, and the burden of showing how you reached your figures sits with you. When KRA disagrees it issues an assessment, and the law gives one route to challenge it: an objection lodged with the Commissioner, then an appeal to the Tax Appeals Tribunal.
1. What an assessment is, and how a dispute starts
KRA decides that tax, penalty or interest is due. The Tax Procedures Act defines an assessment to include a self-assessment, a default assessment, an advance assessment, an amended assessment, and any other assessment made under a tax law.
A small business most often meets the default assessment, which KRA raises under section 29 of the Tax Procedures Act where a return was not filed; the Income Tax Act power behind it is section 73(3). KRA also raises additional assessments after an audit, where it has examined your records and concluded that the figures you declared are too low.
KRA usually engages before it assesses. It asks for documents, records and other information to verify your self-assessment, and where it finds gaps it tells you, orally and in writing, and asks you to respond before a demand or assessment is issued. The records you produce in that engagement are the ones that decide an objection later.
2. The thirty-day window
Section 51(2) of the Tax Procedures Act gives you thirty days from the day you are notified of the decision to lodge a notice of objection in writing with the Commissioner. Under section 77(2), computing this thirty-day period does not include Saturdays, Sundays, or public holidays.
The period runs from the date the decision was effectively notified or served on you, not from the date printed on the letter and not from the date you happened to open or read an iTax notice. Keep proof of the notification: a stamped copy, a portal acknowledgement, or the iTax record.
If the thirty days have passed, apply in writing to the Commissioner for an extension of time to lodge the objection under sections 51(6) and 51(7). The Commissioner may grant it where absence from Kenya, sickness or another reasonable cause prevented you from lodging on time, and where you did not unreasonably delay once you could act. If that is refused, the refusal is not an objection decision, so it cannot be appealed to the Tax Appeals Tribunal; it can be challenged only by judicial review. The internal route is still expected to be exhausted first.
3. What makes an objection valid
Section 51(3) sets three conditions.
The notice must state precisely the grounds of objection, the amendments required to correct the decision, and the reasons for those amendments. A letter that calls the assessment excessive without saying which figure is wrong and why does not meet the test.
Where the objection is to an assessment, you must have paid the entire amount of tax due that is not in dispute, or applied for an extension of time to pay under section 33(1).
All the documents relevant to the objection must be submitted.
If KRA decides the objection was not validly lodged, it must notify you in writing within fourteen days, and must ask you to submit the missing information within seven days. If you do not, KRA may make an objection decision within sixty days of the date you lodged. Submit the information requested within the seven days specified in the notice.
Where the decision you are objecting to is an amended assessment, you may object only to the alterations and additions made to the original assessment, under section 51(5).
4. Paying the part you do not dispute
If the assessment is KES 5,000,000 and you accept KES 1,000,000 of it, you must pay the KES 1,000,000 for the objection to be valid. The KES 4,000,000 you dispute does not have to be paid to lodge the objection.
If you cannot pay the undisputed amount, apply in writing for an extension of time to pay. The Commissioner may grant it, or require the tax in instalments, where there is reasonable cause, and must notify you of the decision within thirty days of receiving the application. Default on an instalment makes the whole balance payable at once, and late payment interest still runs from the original due date.
5. Where and how to file
Objections under section 51(2) are lodged with the Commissioner. KRA's public notice of 29 February 2024 requires the notice of objection and its supporting documents to be uploaded on iTax. Documents that cannot be uploaded go to the Legal Services and Board Coordination email, LSBCIROStaff@kra.go.ke, or are hand-delivered to the Independent Review of Objections offices in Nairobi, Mombasa, Kitengela, Thika, Kisumu, Eldoret and Nakuru.
File the notice of objection on iTax and keep the acknowledgement reference. Where a supporting document cannot be uploaded, send it through the email or delivery channels above and keep a stamped copy or a delivery receipt. That proof shows you lodged inside the thirty days.
6. What KRA must do: the sixty-day rule
Once a valid objection is lodged, KRA must consider it and decide to allow it in whole or in part, or to disallow it. That decision is the objection decision.
The Commissioner must make the objection decision within sixty days from the date of receipt of a valid notice of objection. If no decision is made within that period, the objection is deemed to be allowed. KRA must then notify you in writing and take the steps needed to give effect to the decision, including making an amended assessment where the objection was to an assessment.
The objection decision must include a statement of findings on the material facts and the reasons for the decision.
7. If KRA rejects the objection: the Tax Appeals Tribunal
An objection that is disallowed, in whole or in part, can be appealed to the Tax Appeals Tribunal, a quasi-judicial body set up under the Tax Appeals Tribunal Act and the court of first instance for tax disputes.
The notice of appeal must be lodged within thirty days of receipt of the objection decision. That thirty-day period is computed excluding Saturdays, Sundays, and public holidays under section 77(2). Within fourteen days of filing the notice, you must file a memorandum of appeal, a statement of facts, the decision being appealed, and any supporting documents.
The appeal is valid only if you have paid the tax not in dispute, or entered into an arrangement with the Commissioner to pay it, at the time you lodge the notice, under section 52(2).
You pay a non-refundable fee of KES 20,000 before appealing.
Section 56(3) limits the grounds you can rely on. In an appeal to the Tribunal, the High Court or the Court of Appeal, you rely only on the grounds stated in your objection, unless the Tribunal or the court allows you to add new grounds.
8. Beyond the Tribunal
A party dissatisfied with a Tribunal decision may appeal to the High Court within thirty days of being notified of the decision, or within a longer period the High Court allows. From the High Court, a further appeal lies to the Court of Appeal, again within thirty days. Both appeals are on a question of law only.
Section 56(1) places the burden on the taxpayer to prove that the tax decision is incorrect.
KRA states that a case takes a minimum of two years to conclude at the Tribunal, the High Court and the Court of Appeal.
9. Settling without a hearing
The Act provides for settlement of disputes out of court or Tribunal, and the Tax Appeals Tribunal Act allows the parties to apply to settle at any stage.
Where the court or the Tribunal permits the parties to settle, the settlement must be made within one hundred and twenty days of that permission. If it is not, the dispute goes back to the court or Tribunal that permitted it. Get any agreement in writing and confirm what happens to the remaining assessment, the penalty and the interest.
10. Interest, penalties and payment plans while the dispute runs
Late payment interest runs at one per cent per month or part of a month on the amount unpaid, from the date the tax was due until it is paid, and is computed as simple interest. Under section 38(2), interest you paid is refunded to the extent that the principal amount was later found not to have been payable. Under section 38(8), the accrued interest cannot in aggregate exceed the principal tax liability. A late payment penalty of five per cent of the tax due and payable also applies.
Under section 35(1), a payment that is less than the total amount of tax, penalty and interest due is applied first to the tax, then to the penalty, then to the interest.
KRA can accept an arrangement to pay the tax not in dispute, and it operates payment plans for tax arrears. Ask for the arrangement in writing and keep the approval.
11. What to do before the assessment arrives
Keep the records that support your return for at least five years, because that is the period KRA can normally assess. Where there is gross or wilful neglect, evasion or fraud, KRA can assess at any time. Reconcile your books monthly so a figure on a return matches a figure in your records. Respond to every KRA request for documents within the time given, and keep copies of what you sent.
When a demand or assessment arrives, confirm when the decision was notified or served on you, keep the service record, and calculate the objection deadline from that date. Then start gathering the records that support your position.
Key facts
| Item | Figure | Source |
|---|---|---|
| Objection window | 30 days from notification | Tax Procedures Act, s. 51(2) |
| Validity test | grounds, amendments and reasons; tax not in dispute paid or an extension applied; documents submitted | Tax Procedures Act, s. 51(3) |
| Objection decision | 60 days from receipt of a valid notice, else deemed allowed | Tax Procedures Act, s. 51(11) |
| Tribunal appeal | 30 days | Tax Appeals Tribunal Act, s. 13(1)(b) |
| Memorandum of appeal | 14 days | Tax Appeals Tribunal Act, s. 13(2) |
| Tribunal fee | KES 20,000, non-refundable | Tax Appeals Tribunal Act, s. 12 |
| High Court and Court of Appeal | 30 days, question of law only | Tax Procedures Act, ss. 53, 54, 56(2) |
| Settlement window | 120 days from permission to settle | Tax Procedures Act, s. 55(1) |
| Late payment interest | 1% per month or part of a month, simple interest, capped at the principal tax liability | Tax Procedures Act, s. 38(1), (3), (8) |
| Interest refund | Refunded to the extent the principal was not payable | Tax Procedures Act, s. 38(2) |
| Interest ceiling | Accrued interest cannot exceed the principal tax liability | Tax Procedures Act, s. 38(8) |
| Late payment penalty | 5% of the tax due and payable | Tax Procedures Act, s. 83A |
| Record retention | 5 years | Tax Procedures Act, s. 23(1)(c) |
Frequently Asked Questions
What is the difference between an assessment and a demand?
An assessment is the decision that tax is due. A demand is the request for payment of an amount already assessed or notified. A demand that only repeats an existing assessed debt does not by itself reopen the assessment's objection period. A demand for a penalty or late payment interest is separately a tax decision you can object to, under section 3(g).
Can I object to a penalty?
Yes. A demand for a penalty or late payment interest is a tax decision you can object to.
What if I miss the thirty days?
Apply in writing to the Commissioner for an extension of time to lodge the objection, on the grounds of absence from Kenya, sickness or another reasonable cause. If that is refused, the refusal is not an objection decision and cannot be appealed to the Tribunal; it can be challenged only by judicial review. The internal objection route is still expected to be exhausted first.
Do I need a lawyer?
Not for the objection itself, which is an administrative process. For a Tribunal appeal, most taxpayers use an advocate or a tax agent, and the burden of proof is on you.
How long does the whole process take?
KRA states a minimum of two years to conclude a case at the Tribunal, the High Court and the Court of Appeal.
Sources and review record
Sources in this guide were checked on 28 October 2026. Official details can change.
- Tax Procedures Act, No. 29 of 2015, ss. 23, 29, 31, 33, 35, 38, 51 to 56, 77(2) and 83A: Kenya Law and KRA
- Tax Appeals Tribunal Act, No. 40 of 2013, ss. 12 and 13: Kenya Law
- KRA public notice, 29 February 2024, service of objection notices: kra.go.ke
- KRA, tax assessment FAQ: kra.go.ke
- Income Tax Act (Cap. 470), s. 73(3): KRA
- Chambers and Partners, Tax Controversy 2026: Kenya: practiceguides.chambers.com
Stay updated
 Stay updated
Get the next guide in your inbox.